Area Details
Jumeirah Village Circle
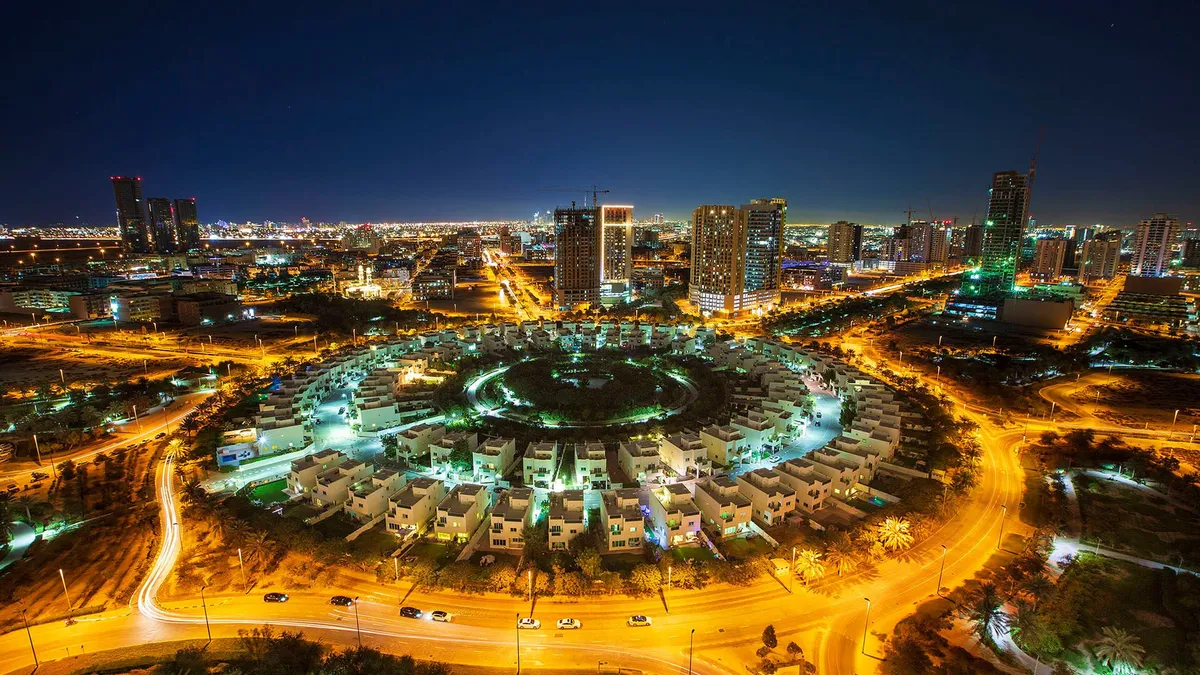
Jumeirah Village Circle (JVC) is one of Dubai’s well-known residential districts. Developed by Nakheel, it is worth reviewing for different buyer groups because of its mix of apartment options, a smaller villa component, everyday services, and access to several of the city’s main routes. Nakheel describes the district as a circular residential community with parks, sports facilities, and access from Sheikh Mohammed Bin Zayed Road, Al Khail Road, and Hessa Street. For end users, JVC’s appeal is mainly linked to unit variety, local services, a relatively neighbourhood-style setting, and the ability to choose among many buildings. For investors, the area’s relevance is more closely tied to the depth of apartment transactions, the volume of existing and under-construction supply, and the variation in quality between projects. Therefore, a buying decision in this district should not be based only on the area name or a single headline rate; the building, unit, tenancy status, service charges, handover timing, and nearby competing projects all need to be reviewed.
Snapshot
Short Overview
Jumeirah Village Circle (JVC) is one of Dubai’s well-known residential districts. Developed by Nakheel, it is worth reviewing for different buyer groups because of its mix of apartment options, a smaller villa component, everyday services, and access to several of the city’s main routes. Nakheel describes the district as a circular residential community with parks, sports facilities, and access from Sheikh Mohammed Bin Zayed Road, Al Khail Road, and Hessa Street.
For end users, JVC’s appeal is mainly linked to unit variety, local services, a relatively neighbourhood-style setting, and the ability to choose among many buildings. For investors, the area’s relevance is more closely tied to the depth of apartment transactions, the volume of existing and under-construction supply, and the variation in quality between projects. Therefore, a buying decision in this district should not be based only on the area name or a single headline rate; the building, unit, tenancy status, service charges, handover timing, and nearby competing projects all need to be reviewed.
Full Guide
About Jumeirah Village Circle
Overall Area Identity
In terms of land use, JVC is primarily an apartment-led residential district. Transaction and supply data indicate that apartments account for the main share of both inventory and transaction activity, while villas and offices play a more limited role. This composition matters for buyers because it shows that competition, liquidity, and pricing comparisons are deeper in the apartment segment than in other asset groups.
From a residential-experience perspective, the area is most relevant for buyers who value car access, everyday services, a broad range of apartment options, and a neighbourhood-style environment. However, the quality of the experience in JVC depends heavily on the building and the exact unit location. Two units of similar size can produce very different outcomes for a buyer because of differences in developer quality, building management, amenities, parking, view, floor level, and service charges.
Location and Access
JVC is positioned in a part of Dubai that can be reached from several major routes. Nakheel refers to access from Sheikh Mohammed Bin Zayed Road, Al Khail Road, and Hessa Street. This is important for residents who rely on cars, but in practice the building’s exit route, peak-hour travel time, and actual distance to daily destinations should be assessed separately.
In terms of public transport, the Roads and Transport Authority adjusted bus route J01 so that it operates inside JVC. In 2026, the Government of Dubai also announced the expansion of bus-on-demand service to JVC. These are positive points for users who need public or mixed transport options, but the real access time to stops, daily route, and peak-hour connectivity should still be checked for each building.
For road infrastructure, an official announcement about cooperation between the Roads and Transport Authority and a development entity referred to a plan to add four entry and exit points for JVC and improve access capacity. This may be relevant from a future-access perspective, but it should not be interpreted as a guarantee of price impact or investment outcome.
Lifestyle and Everyday Services
Lifestyle in JVC is largely shaped around everyday residential use, local services, retail, in-building amenities, parks, and open spaces. In its official description of the district, Nakheel refers to parks, jogging trails, a football pitch, sports courts, a padel court, a gym, and a local mall. This mix is worth reviewing for residents who want many daily needs to be met within or near the district.
For families, school access and the daily commute are important. The official Dubai school directory lists schools located in Jumeirah Village Circle South. However, school selection should not be based only on proximity; curriculum, availability, fees, commute time, academic calendar, and suitability for the child’s age should all be reviewed separately.
Property Profile and Asset Types
JVC’s property profile is mainly apartment-based. In the supply data, 51,631 completed residential units and 34,013 under-construction residential units were identified. Of these, 49,604 completed units and 33,886 under-construction units are apartments. This composition shows that apartments are the core of the district’s market, and that buying decisions, especially for investors, should be made carefully at project and building level.
In the villa segment, 2,027 completed units and 127 under-construction units were identified. Villas in this district have less depth than apartments in terms of data volume and supply. As a result, villa purchases require more case-by-case review, including plot size, renovation condition, privacy, parking, maintenance quality, internal layout, and position within lower-density clusters.
In the office segment, completed office space was recorded at 443,792 sq ft, while under-construction office space was recorded as zero. This figure is reported only as office space, and no office unit count has been derived from it. The office role of the district is visible, but JVC’s dominant identity remains residential.
Benchmark Rate for Secondary-Market Transactions
In this guide, the benchmark rate means the median secondary-market transaction price per square foot. The rate has been calculated separately for each property type, and no blended public benchmark has been created.
| Property type | Secondary-market benchmark rate, AED per sq ft |
| Apartment | 1,324.8 |
| Villa | 1,036.9 |
| Office | 1,261.6 |
These figures are starting points for analysis, not fixed prices for any individual unit. The final price of a property can vary because of the building, floor level, view, tenancy status, maintenance quality, service charges, layout, parking, developer, payment terms, and legal status. The apartment segment has stronger transaction depth; villas and offices also have usable data, but interpretation should be more cautious and more case-specific.
Pricing Table by Property Type
| Property type | Median size, sq ft | Secondary market: median total price, AED | Secondary market: AED per sq ft | Primary market: median total price, AED | Primary market: AED per sq ft |
| Apartment | 744 | 932,358 | 1,324.8 | 1,080,000 | 1,570.0 |
| Office | 1,145 | 1,363,700 | 1,261.6 | 2,402,936 | 1,894.2 |
| Villa | 3,072 | 3,000,000 | 1,036.9 | 4,250,000 | 1,217.2 |
| Studio apartment | 412 | 634,781 | 1,516.4 | 759,379 | 1,849.3 |
| 1-bedroom apartment | 790 | 1,000,000 | 1,302.8 | 1,154,926 | 1,479.5 |
| 2-bedroom apartment | 1,238 | 1,495,387 | 1,193.1 | 1,735,500 | 1,383.1 |
| 3-bedroom apartment | 1,341 | 1,975,000 | 1,325.5 | 2,279,050 | 1,646.9 |
| 3-bedroom villa | 3,114 | 2,875,000 | 917.5 | 4,562,500 | 1,425.7 |
| 4-bedroom villa | 3,329 | 3,357,500 | 1,083.9 | 4,200,000 | 1,163.2 |
The difference between primary-market and secondary-market prices in some rows may relate to factors such as handover timing, project amenities, payment terms, construction status, developer quality, and project pricing strategy. This difference should not be treated as either an advantage or a disadvantage on its own. For a more precise decision, similar units in the same building or competing projects should be compared with like-for-like payment terms and handover timing.
Supply, Under-Construction Stock, and Its Effect on Buying Decisions
One of the most important points in JVC is the high volume of under-construction stock. In the residential segment, 34,013 under-construction units were identified, almost all of which are apartments. This has different implications for end users and investors.
For end users, new supply can mean more choice, newer layouts, and more up-to-date amenities. At the same time, handover timing, delay risk, construction quality, developer track record, service charges, and surrounding density should be reviewed.
For investors, under-construction stock can increase future competition. Therefore, buying in an active transaction area is not enough on its own. Entry price, differentiation from nearby competing projects, unit size, rental demand, amenity level, building management, and the ability to exit at the right time should all be assessed together.
In the Dubai 2040 Urban Master Plan, Dubai Municipality emphasizes better use of space and infrastructure, the creation of healthy and active communities, more parks and open spaces, and improved access with a people-centric approach. This direction matters for residential districts that are still maturing, but it should not be used as a definite price forecast or investment outcome.
Residential and Office Occupancy
The latest residential occupancy rate in the reviewed period is 85.7% for the second half of 2025. The office occupancy rate for the same period is 93.0%. These figures show that usable data exists for both the residential and office segments, but interpretation should be made alongside future supply, property quality, entry price, tenancy status, and the buyer’s objective.
Occupancy alone does not determine the investment outcome. A building with better management, stronger amenities, easier access, or more reasonable service charges may perform differently from the area average. Conversely, a building with high direct competition, weak maintenance quality, or elevated costs may be unsuitable for some buyers even within an area with generally usable data.
Which Buyers Should Review JVC?
JVC is worth reviewing for buyers looking for varied apartment options, car access, local services, and multiple choices across different budgets. The district may be relevant for end users, couples, small families, and people who want access to several business or leisure corridors in Dubai.
For investors, the area is more analyzable in the apartment segment because apartment transactions and apartment supply are deeper than other groups. However, investors should avoid making decisions based only on the benchmark rate. In JVC, differences between buildings can be significant; therefore, project selection, not just area selection, is a core part of the decision.
Advantages and Considerations
JVC’s key reviewable advantages include apartment variety, sufficient transaction data in the apartment segment, access to main routes, everyday services, local amenities, and a relatively established residential community. The availability of a reliable apartment benchmark helps buyers compare a unit’s price against similar transactions more effectively.
There are also several important considerations. First, the volume of under-construction stock is high and may increase future competition. Second, building and developer quality are not uniform, which means the area average is not enough for a final decision. Third, public transport and commute time should be checked separately for each building. Fourth, villa and office data are usable, but they have less depth than the apartment segment.
Homeland Advisory View
Homeland’s view is that JVC is worth reviewing through a data-led decision-making lens, especially in the apartment segment. The secondary-market benchmark rate can provide a useful starting point for comparison, but the final decision should be made at project and unit level.
In this district, the core question is not whether JVC is suitable in general. The more precise question is which building, at what entry price, with what tenancy status, service charges, construction quality, and nearby competition, aligns with the buyer’s objective. For end users, quality of life and daily commute should be priorities. For investors, entry price, liquidity, future supply competition, and the unit’s fit with rental demand should be reviewed together.
Frequently Asked Questions
Is buying property in JVC suitable for all buyers?
No. JVC is worth reviewing for certain scenarios, especially for buyers who want varied apartment options, local services, and car access. However, buyers who need metro access, beach proximity, a very low-density setting, or fully walkable access should compare it with other districts.
How should the secondary-market benchmark rate in this area be interpreted?
The benchmark rate is the median secondary-market transaction price per square foot. It is not the fixed price of any individual unit and should be adjusted for building quality, floor level, view, tenancy status, service charges, parking, developer, and legal status.
What type of buyer or investor is this area most relevant for?
The area is most relevant for buyers who need varied apartment options, different budget ranges, and everyday services. For investors, JVC is more worth reviewing when the entry price, project quality, tenancy status, and future supply competition align with the buying objective.
What considerations should be reviewed before making a decision in this area?
Under-construction supply, building quality, service charges, tenancy status, commute route, parking, developer reputation, building management, and comparisons with similar projects should all be reviewed. For primary-market purchases, handover timing and payment terms are also important.
Is villa data in this area as strong as apartment data?
No. Villa data is sufficient for calculating a benchmark rate, but it is less deep than apartment data. Therefore, villa purchases in JVC require a more detailed review of the property, plot, renovation condition, location, and similar transactions.
Is JVC sufficient for investment only because apartment transaction volume is high?
No. Transaction volume can support analysis, but it is not enough on its own. Investors should review entry price, project quality, service charges, tenancy status, competition from new projects, and exit plan.
Is the presence of under-construction stock a positive point or a risk for buyers?
It can be both. On one hand, under-construction stock creates more choice and may offer newer layouts and amenities. On the other hand, new supply can increase rental and resale competition. The outcome depends on project quality, entry price, and handover timing.
If your objective is investment, reviewing the entry price, project quality, service charges, tenancy status, and future supply competition is important. Homeland can review selected options against the available data, your budget, and your investment objective before